8th Circuit Court ruling ends Biden-era SAVE plan, forcing more than 7 million borrowers to seek new student loan repayment options
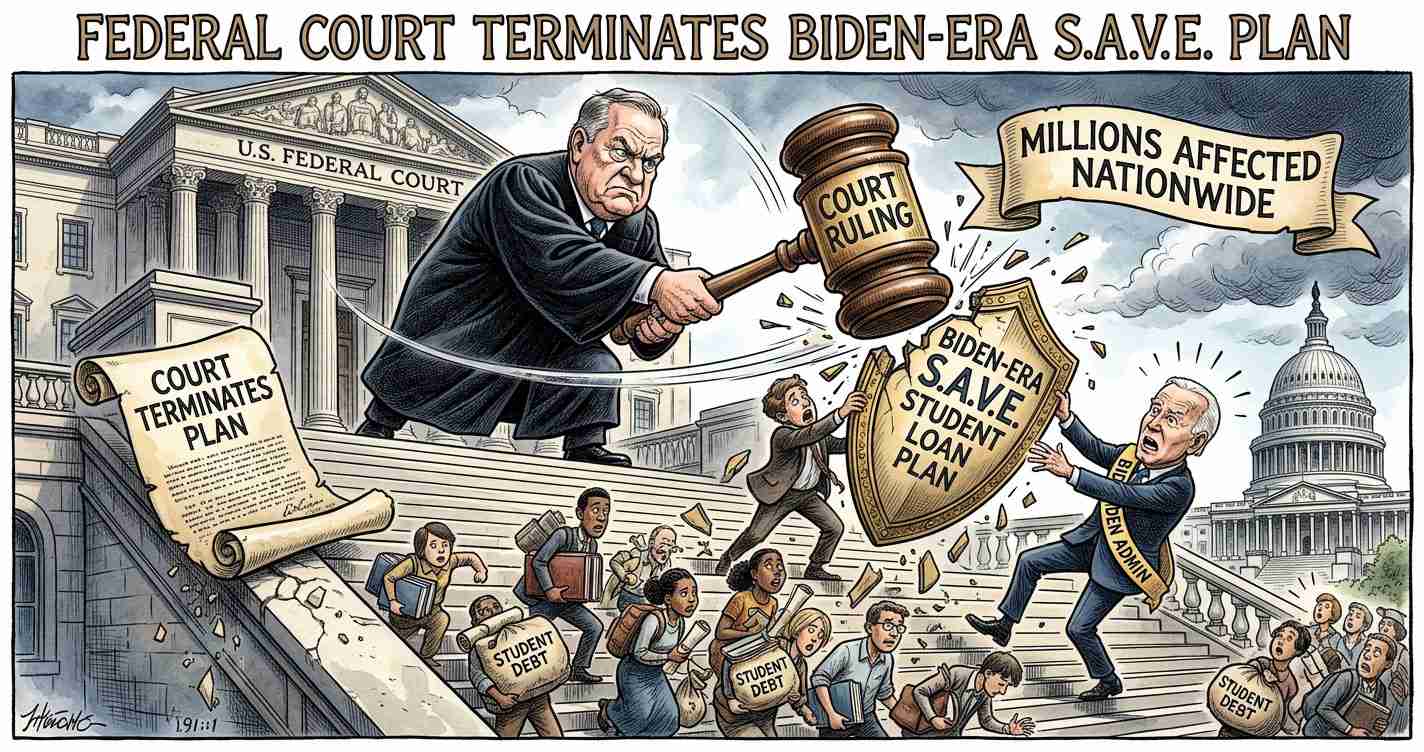
The U.S. Court of Appeals for the 8th Circuit on March 9, 2026, finalized the termination of the Biden-era SAVE plan, affecting more than 7 million federal borrowers—who must now choose lawful alternative repayment options without delay.
Key takeaways
- 8th Circuit decision (March 9, 2026) reversed a lower-court dismissal and removed SAVE from federal regulations, blocking new enrollments and denying pending applications.
- More than 7 million borrowers were enrolled in SAVE by late 2025; about 450,000 applications were pending at that time.
- Borrowers must act: use the Loan Simulator and contact servicers to choose new repayment plans and protect PSLF credit.
Main
What the 8th Circuit decision did
On March 9, 2026, the U.S. Court of Appeals for the 8th Circuit reversed a February dismissal by U.S. District Judge John Ross and finalized an order ending the Saving on a Valuable Education (SAVE) plan. By joint motion, the parties and the court removed SAVE from the Code of Federal Regulations except that months placed in forbearance or deferment under the program will still count toward income-driven repayment (IDR) forgiveness where permitted. The decision:
- Blocks new SAVE enrollments.
- Denies or halts pending SAVE applications.
- Requires existing enrollees to transition to alternative repayment plans or risk automatic placement into other options by servicers.
Official department context is provided in the U.S. Department of Education press release, and reporting on the termination is summarized by The College Investor.
Legal background and timeline
SAVE was introduced in 2023 and promoted as an exceptionally affordable IDR plan—capping or reducing many monthly payments, sometimes to $0, and subsidizing unpaid monthly interest so balances would not grow. Republican-led states, including Missouri, argued the program constituted unauthorized mass forgiveness beyond the department’s authority and would cost taxpayers substantially. Litigation and injunctions proceeded through 2024–2026, including a prior 2025 8th Circuit injunction and a February 2026 district-court dismissal that the appeals court reversed on March 9, 2026.
- SAVE features: interest subsidy, lower payments, and faster path to forgiveness for many enrollees.
- Litigation: multiple states challenged legality, leading to injunctions and appeals that culminated in the current ruling.
Why the government and plaintiffs settled
On Dec. 9, 2025, the Department and Missouri filed a proposed settlement to remove SAVE from the federal regulations. The settlement preserved counting rules so that months in forbearance or deferment under SAVE would still count toward IDR forgiveness and Public Service Loan Forgiveness (PSLF) where applicable. The department framed the move as protecting borrowers by moving them into lawful repayment plans and safeguarding certain forgiveness credits; plaintiffs emphasized limits on administrative authority.
Read the department’s announcement: U.S. Department of Education press release.
Impact on borrowers now enrolled in SAVE
More than 7 million borrowers enrolled in SAVE by late 2025 must take prompt action. The Education Department reported that some loans were placed in forbearance and interest began accruing on certain accounts as of Aug. 1, 2025. Without borrower selection of a new plan, servicers may move accounts into default repayment options that could raise monthly bills or lengthen repayment.
Action is urgent: use the Loan Simulator and contact your servicer to select an appropriate plan.
Official guidance and transition details are available from the Education Department.
Available student loan repayment options
With SAVE terminated, borrowers should review lawful alternatives. Key options include:
- Income-Based Repayment (IBR): sets payments at approximately 10%–15% of discretionary income with 20–25 year terms for qualifying loans. Available for loans made before July 1, 2026.
- Repayment Assistance Plan (RAP): created by the One Big Beautiful Bill Act (OBBBA) and effective July 1, 2026, RAP uses a sliding scale (1%–10% of AGI), requires 30 years of payments for participants, and may set a minimum payment; it will be the new IDR option for loans made after July 1, 2026.
- Standard, Graduated, and Extended plans: remain available; the 10-year Standard plan commonly yields the lowest total interest paid.
Summary analysis of upcoming changes is available from university financial-aid reporting: Financial Aid reporting.
Public Service Loan Forgiveness (PSLF) and frozen progress
Borrowers pursuing PSLF must verify and preserve qualifying months. The settlement preserves counting of months that were in SAVE forbearance or deferment toward PSLF and IDR forgiveness where applicable, but borrowers should certify employment and file any overdue paperwork to reclaim credit for months where SAVE progress was effectively frozen.
Guidance and tools are available at StudentAid.gov.
Broader 2026 changes to federal student loans
- New loans made after July 1, 2026 will generally be limited to the Standard plan or RAP as the only IDR option for new borrowing.
- Borrowing limits will be tightened and deferment/forbearance periods scaled back in many cases (examples include caps such as nine months or two years depending on relief type).
- There may be tax implications for IDR forgiveness after 2025 outside of PSLF; PSLF forgiveness remains exempt from federal tax.
See analysis at Financial Aid.
What borrowers should do now
- Use the Loan Simulator: visit the Loan Simulator at StudentAid.gov to compare repayment plans and estimate payments under IBR, RAP, and other options.
- Contact your loan servicer to avoid automatic assignment into a repayment plan that may not fit your needs.
- PSLF claimants: certify employment and submit any overdue forms to reclaim months that counted while SAVE was in effect.
Sources and reporting notes
This article is based on official Education Department materials and financial-aid reporting. Key sources:
- U.S. Department of Education press release
- The College Investor coverage
- University financial-aid summary of 2026 loan changes
- Loan Simulator (StudentAid.gov)
Implications for the United States
Economic impact: Ending SAVE shifts costs and payment burdens; administration estimates and opponents offered differing cost figures, with plaintiffs arguing termination protects federal finances. Borrowers may face higher monthly bills and longer repayment timelines.
Political consequences: The ruling will be portrayed differently across the political spectrum—debates will focus on administrative authority, fiscal impact, and borrower protections. Litigation demonstrated how courts can reshape executive policy.
Social effects: Millions of workers—including teachers, first responders, and health-care providers—must reassess budgets. Some who benefited from SAVE’s interest subsidy will now see balances grow; others must pursue PSLF or alternate plans.
Remember: borrowers should act now—use the Loan Simulator, contact servicers, and file PSLF paperwork where applicable to protect repayment progress and forgiveness credit.